You finally scrape together your first $500. Now what? Half the internet says invest it before inflation eats it. The other half says park it in an emergency fund first. Both sides are half right — and the order you do them in matters more than the amount. Here’s how to think it through, step by step.
What an Emergency Fund Actually Is
An emergency fund is cash you keep in a regular savings account for life’s surprises: a car repair, a busted phone, hours cut at work, a medical bill. It’s not an investment, and it’s not supposed to grow. It has one job — being there, today, at full value, with no drama.
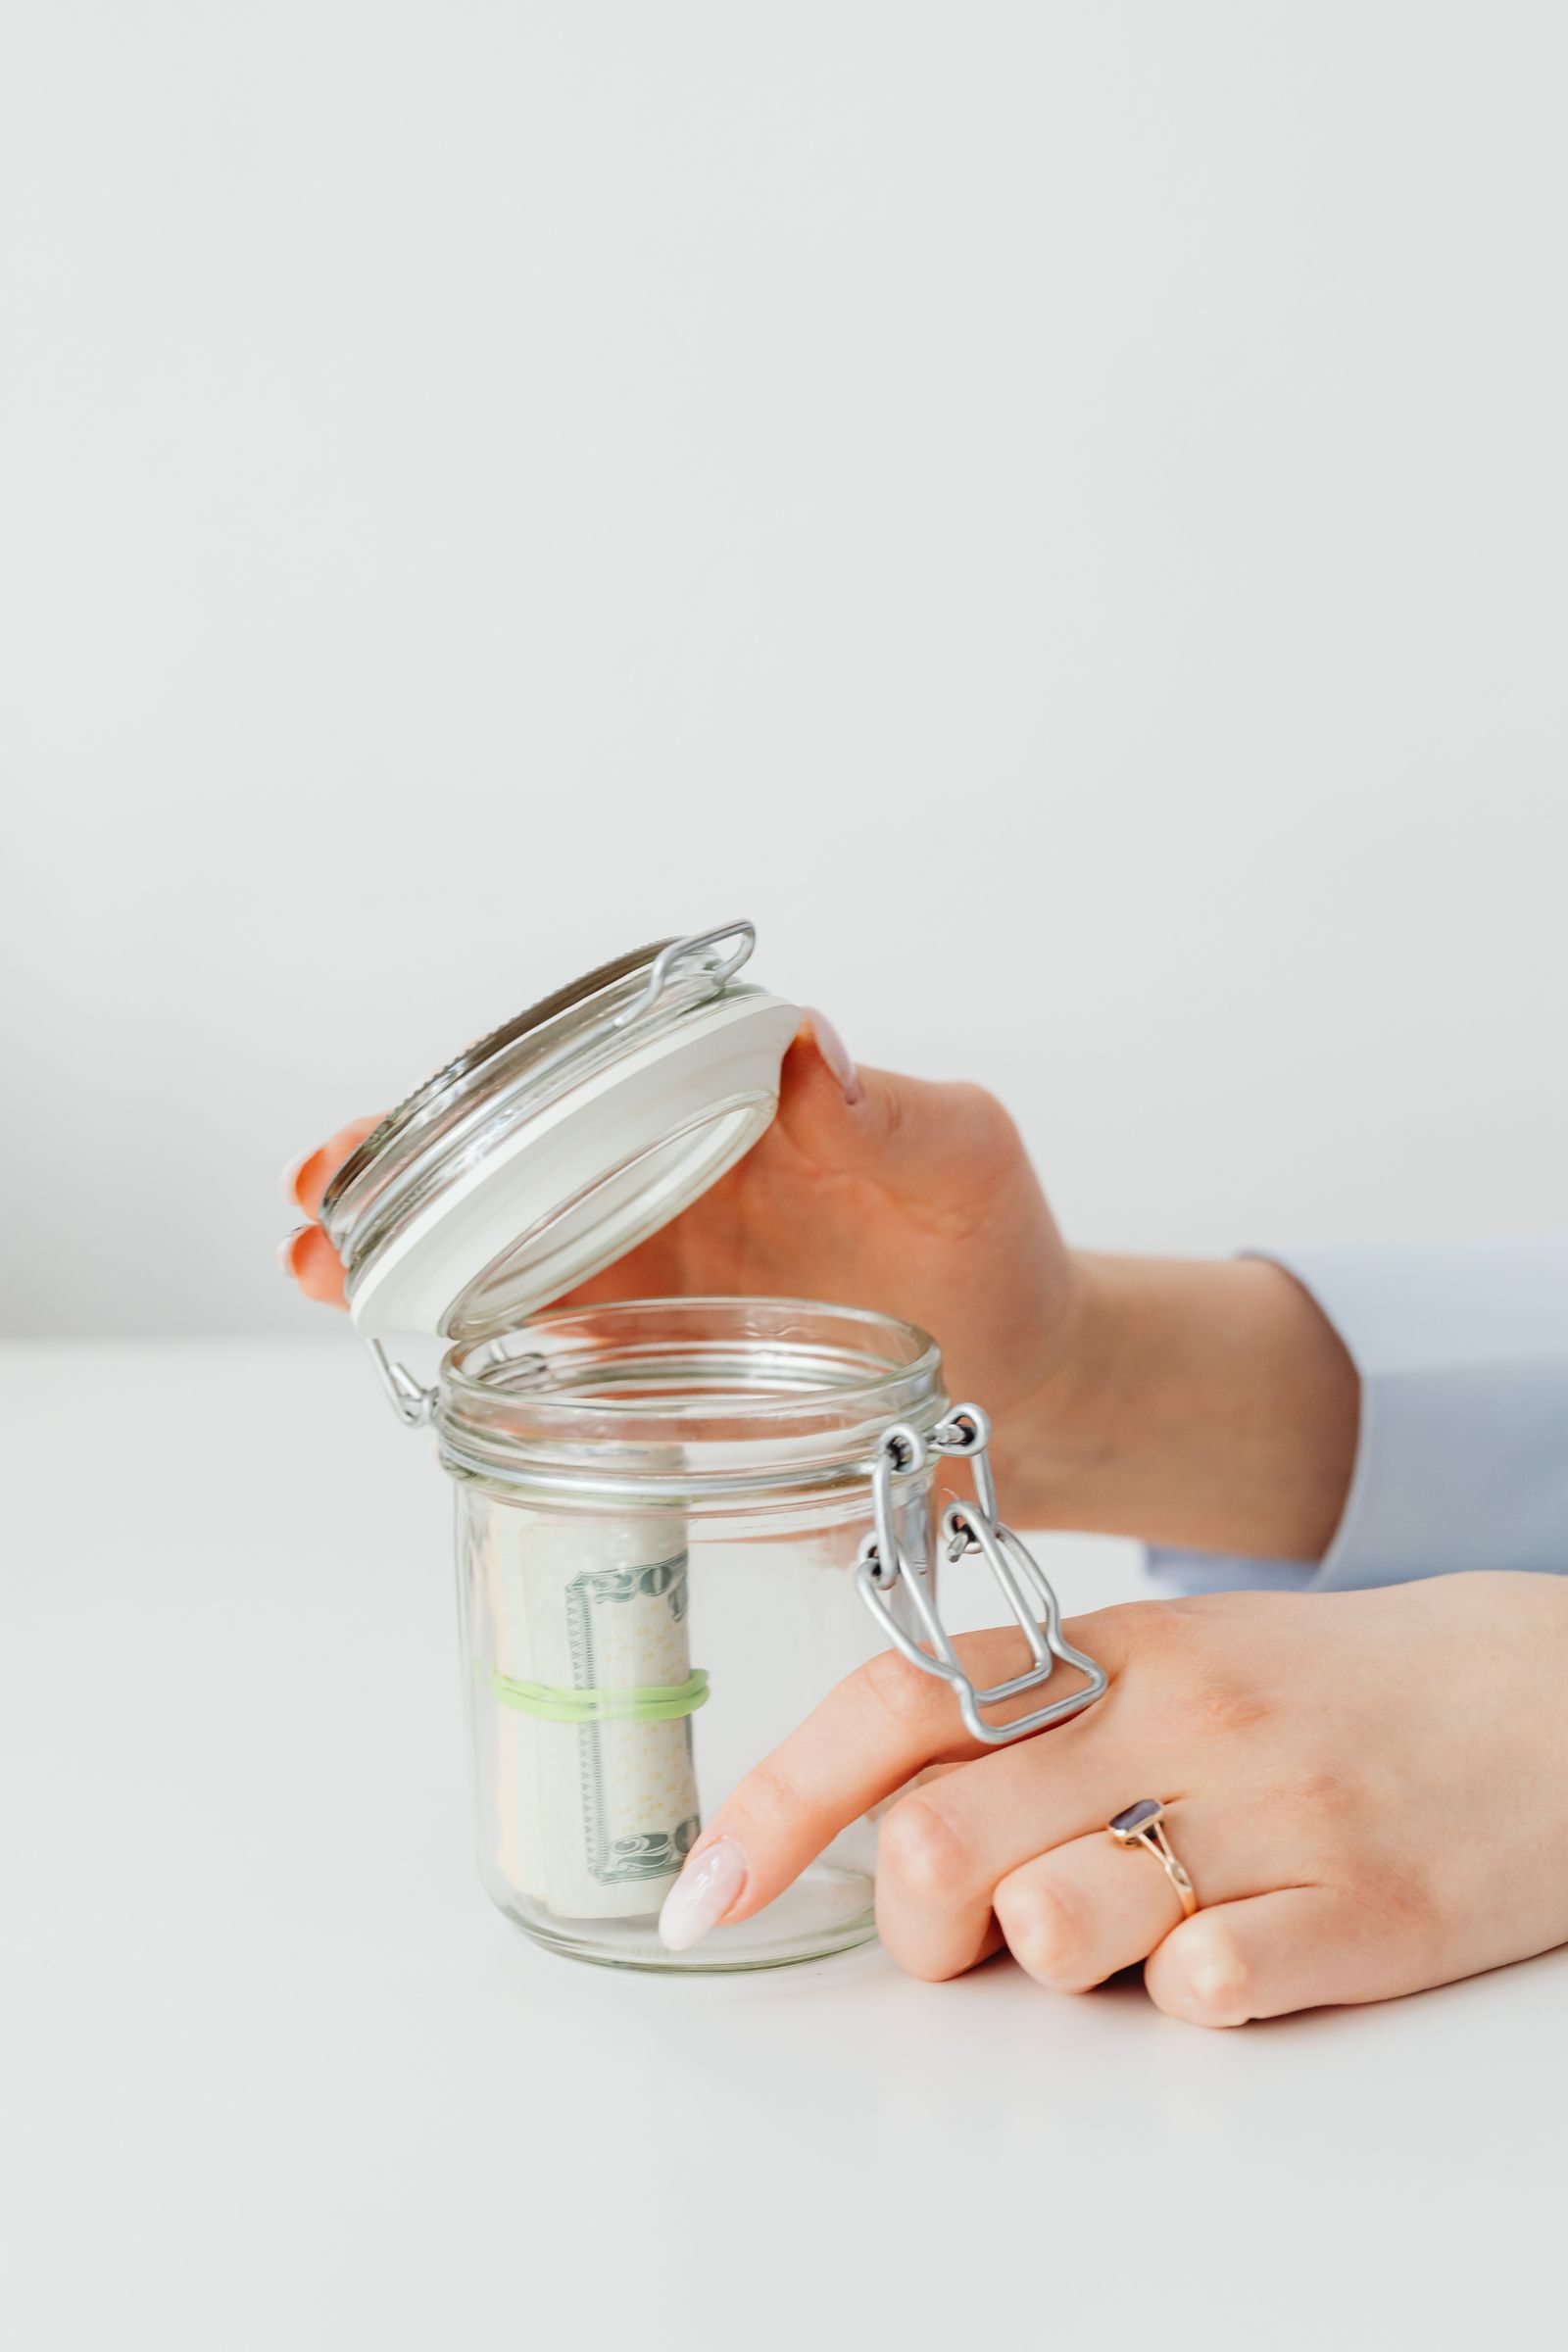
The key word is “emergency.” A flash sale at your favorite store isn’t one. Losing your income for two months is. The fund exists so one bad week doesn’t snowball into a bad year.
Why the Emergency Fund Usually Comes First
Investing has a catch nobody puts on the highlight reel: the market goes down sometimes, and it never checks whether the timing works for you. If all your money is invested and your car dies the same month the market dips 20%, you don’t get to wait for a recovery. You sell at a loss, lock it in — and you still have a broken car.
Without a cushion, emergencies land on a credit card. Then you’re paying steep interest to solve a problem a boring savings account would have handled for free. That’s how people end up “investing” on one side of their finances while quietly drowning on the other.
The Big Exception: Your 401(k) Match
There’s one move that legitimately jumps the queue: grabbing your full employer 401(k) match. A typical match is an instant 50–100% return on that slice of money, and nothing in the market reliably beats free. If your job offers one, contribute enough to get every dollar of it — here’s how the 401(k) match works — even while your emergency fund is still small.
Once the match is captured, though, the emergency fund moves back to the front of the line.
A Simple Order That Works for Most Beginners
If you want a default plan, use this sequence:
- Save a starter cushion — $500 to $1,000 in a savings account. Enough to absorb the most common surprises.
- Grab the full 401(k) match if your employer offers one. Free money outranks everything else.
- Build the fund to one month of essential expenses, then keep going toward three months.
- Invest everything above that. Open the account and start small — you can literally start investing with $100 — and let time do the heavy lifting.
You don’t have to finish one step completely before starting the next. Plenty of people split every paycheck — most of it to the fund, a little to investing — so both grow at once. What matters is that the cushion gets built before investing becomes your whole plan, because compound interest only works if you can afford to leave the money alone.
How Big Should Your Emergency Fund Be?
The classic target is three to six months of essential expenses — rent, food, bills, gas — not three to six months of paychecks. If your income is steady and you’re a student with family you could fall back on, one to three months is a reasonable goal. If your income changes month to month — gig work, tips, freelance — aim for the higher end.
And don’t let the perfect number stop you from starting. A $500 fund that exists beats a $5,000 fund you’re “planning” to build someday. Start where you are.
Frequently Asked Questions
Can I just invest my emergency fund so it grows?
No. That’s the one job this money isn’t allowed to do. Investments can be down 20% in exactly the month you lose your job — the worst possible time to sell. Keep the emergency fund in savings, and let separate money do the investing.
Where should I keep an emergency fund?
In a savings account you can reach within a day or two. A high-yield savings account is a fine choice if there’s no lock-up or withdrawal penalty. Just don’t keep it invested, and don’t keep it in the checking account you spend from every day.
What if I already invested everything and have no emergency fund?
Don’t panic-sell. Pause new contributions, build the $500–$1,000 starter cushion from your next few paychecks, then resume investing once it’s in place.
The Bottom Line
Emergency fund first, investing right behind it — with the 401(k) match jumping the queue. Park your first $500 to $1,000, take every dollar of free match money, build toward three months of essential expenses, then invest the rest without guilt. The emergency fund is never the exciting part of the plan. It’s the part that lets the exciting part survive real life.
Join free — one short email when a new guide drops. Unsubscribe anytime.
This article is for education only and is not financial advice.